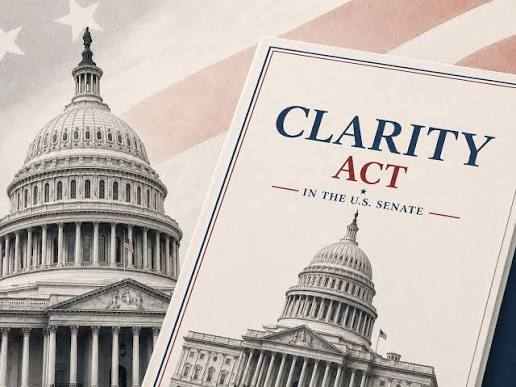
On Tuesday, September 15, the US Senate held a cloture vote on the Digital Asset Market Clarity Act (H.R. 3633).
The result: 49 yes, 50 no, one not voting.
This was a procedural vote, not a vote on passage. It decided only whether the bill could reach floor debate, and it needed 60 votes. It fell 11 short. The market structure bill the crypto industry has pushed for the better part of a decade never even made it to the debate stage.
A Vote That Should Have Been Won
On paper, the conditions were the best they had ever been.
The House passed its version in July 2025 by 294 to 134, with 78 Democrats voting yes. In May 2026, the Senate Banking Committee reported a revised version 15 to 9, with Democratic Senators Ruben Gallego and Angela Alsobrooks crossing over to join Republicans.
On Sunday night, Senator Cynthia Lummis, Banking Chairman Tim Scott and Agriculture Chairman John Boozman released what they called their "last, best and final" text — 635 pages, incorporating what Republicans said were 126 substantive changes requested by Democrats. Earlier disclosures indicated Trump himself had accepted roughly 80% of the ethics framework negotiated by Senators Thom Tillis and Ruben Gallego.
Majority Leader John Thune made the closing case, arguing the bill would help prevent another FTX-style collapse.
Then the voting started.
Every Democrat and independent present voted no — including Gallego and Alsobrooks, who had backed the bill in committee, and including Gillibrand, Warner, Booker, Warnock and Cortez Masto, all of whom had spent months at the negotiating table. Democrat Chris Coons did not vote.
Republicans didn't hold either. Susan Collins of Maine, Josh Hawley of Missouri and Jerry Moran of Kansas all voted no. Tillis also voted no, but as a procedural maneuver: under Senate rules, only a senator on the prevailing side can file a motion to reconsider, so he switched his vote and filed one immediately, preserving the option of bringing the bill back. He posted afterward that this is not the end for the Clarity Act.
Worth noting: at least two of those three Republican no votes had nothing to do with Trump. Hawley objected to the bill's stablecoin yield provisions, which community banks warn would pull deposits out of the banking system. Collins was among a group of Republicans who had raised the same concern. Senators John Cornyn of Texas and John Curtis of Utah had also signaled they were reconsidering on those grounds.
In other words, the bill died along two separate fault lines: one running through the banking industry's deposit anxieties, the other through Democratic objections to the president's conflicts of interest. The first was a technical dispute. The second is what actually killed it.
Ripple CEO Brad Garlinghouse posted after the vote that this one genuinely hurt.
The Ten-Year Question: Who Regulates Crypto?
To judge how bad this failure is, you have to understand what the bill was trying to fix.
The central problem in US crypto for ten years has been jurisdictional: does a given token fall under the SEC or the CFTC? There has never been a statutory answer, only an enforcement answer — regulators sue someone, courts rule, and the industry guesses from there.
CLARITY was designed to convert that guessing into advance knowledge.
It sorts digital assets into three buckets. Digital commodities, defined as assets whose value is intrinsically linked to the use of a decentralized blockchain protocol, go to the CFTC — with Bitcoin and Ethereum written explicitly into the statute, receiving unambiguous legal classification for the first time. Investment contract assets, primarily tokens sold through fundraising, stay with the SEC. Permitted payment stablecoins fall to banking regulators.
Underneath that classification sits a decentralization test — a verifiable standard for determining when a token has become decentralized enough to move from security to commodity.
Beyond classification, the bill would have brought spot trading venues into a federal registration regime for the first time: spot digital commodity exchanges, brokers and dealers all registering with the CFTC, while the SEC retained exclusive jurisdiction over investment contract asset issuers plus anti-fraud and anti-manipulation authority. Exchanges would have to publish source code, transaction history and token economics before listing a new digital commodity. The bill also set statutory terms for self-custody, non-custodial software and rewards on stablecoin balances.
It is the market-structure half of the framework Congress began last year with the GENIUS Act's stablecoin rules — and the harder half.
The 80% Trump Gave Up
To be fair: the concessions in the final text were real, not cosmetic.
The ethics provisions expanded significantly. The draft would bar the president, vice president, members of Congress, senior federal officials and federal judges from personally creating, minting or issuing digital assets — and it defined "sponsorship" as a separate prohibited act. If a covered official supports the creation, issuance or explicit promotion of a digital asset through licensing, revenue sharing, transaction fees or similar arrangements, or authorizes the use of their name, likeness or office to promote one, that could fall within the ban.
For the first time, the bill would require officials to divest certain crypto company holdings. Anyone holding a qualifying "substantial financial interest" would have to sell it or move it into a qualified blind trust.
Penalties got considerably sharper. An official who knowingly and willfully violates the issuance or sponsorship ban would have to disgorge all related profits and pay a civil penalty of either 20% of the consideration received or $500,000, whichever is greater. Digital asset intermediaries would be barred from continuing to offer trading in assets issued in violation, with penalties up to $250,000 per violation per day.
Republicans also dropped the sunset clause. An earlier version would have terminated the ethics enforcement regime once Trump left office — meaning a future Justice Department could never pursue violations from his term. That limitation was removed from the final text. The same text opened a channel for state attorneys general to participate in enforcement, where previous versions had effectively shut non-federal actors out entirely.
Lummis said in a statement before the vote that Trump had agreed to ethics restrictions covering the president, vice president, members of Congress, judges and their spouses — that Democrats had gotten what they asked for and now needed to take yes for an answer.
The White House was blunter. Spokesperson Liz Huston said the president's position was unequivocal: Congress must pass CLARITY so America can stay ahead of foreign competitors and lead the world in innovation.
The 20% Democrats Wouldn't Drop
The Democratic objection was no longer about whether the bill contained ethics provisions. It was about whether those provisions could actually be enforced. Three things stood in the way.
First: who holds the enforcement power.
Opening a channel for state attorneys general did not change the core structure. For the president and other covered officials, the Attorney General remains the only party who can bring a direct civil enforcement action under the statute. A state AG cannot sue the president, cannot ask a court to fine him, cannot seek disgorgement, cannot force divestment. The single thing a state AG can do is sue the Attorney General to challenge federal non-enforcement.
Democrats fixated on this for a specific reason. The current Attorney General, Todd Blanche, spent years as Trump's personal attorney. At a congressional hearing in July, he slipped and said "I am his lawyer" before correcting himself to "was."
And even reaching that step means passing a second gate. Under the draft, if the relevant ethics office has already issued a legal opinion finding that conduct is not prohibited, a state AG cannot bring the suit at all. For the president, that office is the Office of Government Ethics — an entity inside the executive branch.
Senator Elizabeth Warren, ranking member on Senate Banking, called the arrangement a "weak fig leaf" on the floor the night before the vote, describing it as an off switch for enforcement. Her point, roughly: state attorneys general can't take enforcement action against the president — all they can do is sue Trump's former personal lawyer and try to make him act.
Second: the separation isn't clean.
The final text applies the issuance and sponsorship ban only to digital assets issued or sponsored on or after the ethics title takes effect. Even if the bill became law, it could not reach Trump's earlier issuance of $TRUMP, and the disgorgement mechanism could not claw back income already earned.
No retroactivity doesn't mean blanket immunity — holdings meeting the "substantial financial interest" definition would still have to be dealt with before the title takes effect. But the operative word is "dealt with," not "sold." A qualified blind trust is an acceptable alternative.
A blind trust does sever management control and information flow. It does not sever the economic interest. Under the existing Ethics in Government Act, a qualified blind trust does not require the original owner to surrender beneficial ownership. The official, their spouse or qualifying children can remain beneficiaries of both principal and income.
In practice: an official may have no idea how the trustee is managing the assets, and still profit from every gain those assets produce.
This is the real philosophical split between the two parties. The Republican version aims to cut the president's direct control over his private assets — on the theory that if he cannot manage the business, direct the investments or see the transactions, the risk of using public power to actively grow private wealth drops. Hardline Democrats want full economic divestment, arguing that even with a third party at the controls, the president still has a live financial stake while setting policy for the entire industry.
Third: the definitions leave openings.
Under the bill, a "substantial financial interest" means an official holds at least $15,000 of equity in a company or its subsidiary, where issuing or sponsoring digital assets constituted that company's single largest revenue source in at least one of the past three calendar years.
Look at how that threshold is drawn. It doesn't require crypto revenue to exceed 50% of the total — only to exceed any other single line item. That sounds strict and isn't. A company can be deeply dependent on crypto and still fall outside the definition, as long as its revenue is diversified enough: token sales, stablecoin reserve income, transaction fees, lending, custody, investment returns each taking a slice, with issuance and sponsorship never the largest.
Family coverage leaves another opening. The final text covers officials and their spouses. It does not cover adult children.
One of the last Democratic amendments offered on vote day would have extended the ethics provisions to Trump's adult children and required officials with large crypto holdings to sell outright rather than use a blind trust. Lummis rejected it. Negotiations collapsed in Tillis's office hours before the vote.
Warren's core charge is that Trump took in more than $1.4 billion from crypto ventures in his first year in office — the bulk of his income — and that this bill will not stop him from earning the next $1.4 billion. She also offered the political rationale for voting no: the Senate's first order of business after August recess wasn't a bill to make life more affordable for American families, or a bill to end a war, but a bill that would boost the value of the president's crypto empire and reward the crypto billionaires who enabled it.
Senator Mark Warner of Virginia best captured where the talks broke. He said the two sides had come close to resolving the hardest outstanding issues around law enforcement and national security, but the failure to address this fundamental conflict of interest made it impossible for him to support moving forward.
A technical piece of market-structure legislation died in a fight over one man's personal fortune. For the industry, that's the most frustrating way to lose — not because the proposal was flawed, but because the proposal became someone else's bargaining chip.
Is a Failed Bill Actually Bad for Crypto?
In the short term, yes.
The window is closing. Midterms arrive in November and members are heading home to campaign. The House has already cancelled its last two weeks of September. Even if the Senate revived and passed the bill, the House couldn't act until after the election — and next year's Congress may well be split, making passage harder still. One Republican Senate aide told reporters flatly that he considers the bill dead. Alsobrooks insists it isn't, arguing Republicans forced a vote before the ethics dispute was settled.
Markets responded immediately. Bitcoin slipped toward $76,000, and crypto-linked equities including Circle, Bullish and Coinbase fell with it. Going into the vote, prediction markets had already priced passage at 17% to 18%.
But stretch the time horizon and "bad" needs qualifying.
Regulation hasn't stopped. The SEC and CFTC are both advancing rulemaking. SEC Chairman Paul Atkins spent the day before the vote urging Congress to move the bill while making clear the agencies would proceed regardless. Grayscale called the result "not the outcome we hoped for" while emphasizing that regulatory work continues. What the industry lost is statutory certainty, not rules altogether. The difference matters: agency rules can be reversed by the next chairman, statutes cannot.
A bad bill that passes is also not obviously better than a good bill that doesn't. How the decentralization test gets designed, and where its threshold sits, determines which projects survive and which must register as securities. Forcing that through while both sides were still fighting over the language could leave more ambiguity than exists today, not less. Tillis preserving the motion to reconsider suggests the negotiation itself isn't finished.
The most concrete loss is subtler than a price move. It's institutional time.
A firm that wants to run a compliant spot digital commodity business in the US still doesn't know who to register with, what custody standard applies, or which tokens it can list. It can operate under existing agency rules, but it carries the risk that those rules get reversed. That uncertainty shows up directly in capital allocation. Cardano Foundation CEO Frederik Gregaard said before the vote that developers can't wait for America to sort itself out, and that the EU is now the clearest jurisdiction in the world.
So the real consequence isn't how far the price fell. It's that another cohort of teams just moved the US one slot down the list.
The endpoint of this fight is a question more basic than jurisdiction: when Congress rewrites the rules for an entire industry, how much economic distance should exist between that industry and the people writing and enforcing the rules?
Until that has an answer, every crypto bill will function as a confidence vote on the president rather than a vote on policy. No amount of industry lobbying fixes that.
One more thing worth sitting with. The crypto industry has spent ten years demanding a law, on the grounds that you can't build a business without rules. And for those same ten years, it grew into what it is today without them.
Which raises the real question: who was this law protecting — the whole industry, or the firms large enough to need a compliance identity before traditional finance will take their call?
For the first group, this was a delay.
For the second, it was a real cost.
The part of the industry still living on regulatory arbitrage didn't lose anything at all.